Eigenvalues & Eigenvectors
Part of the AI Engineer Roadmap
In short
PCA, one of the most used tricks for shrinking big datasets, is built on eigenvectors. They show the directions a matrix only stretches, which tells you where your data varies most.
Special vectors that only get scaled (not rotated) by a matrix transformation — the math underlying PCA, dimensionality reduction and understanding data variance.
Think of it like this
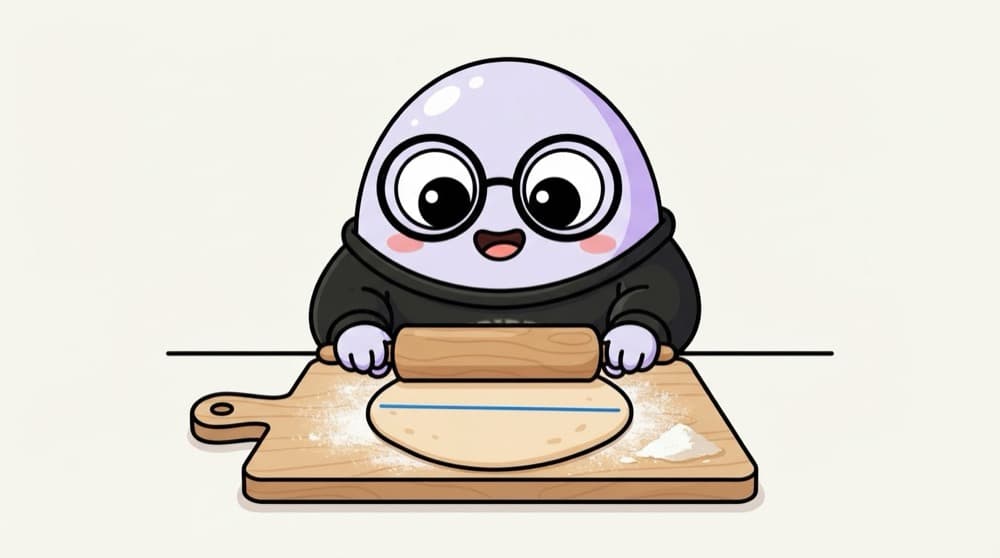
Rolling out a roti
Draw a few lines on a ball of dough and roll it in one direction. Most lines tilt and twist. But the line along the rolling direction just gets longer, it never turns. That line is an eigenvector, and how much longer it got is the eigenvalue.
Watch it happen
Apply A = [[2, 1], [1, 2]]
Vector [1, 0]
- Becomes [2, 1]
- Changes direction, tilts upward
- No single stretch factor
Eigenvector [1, 1]
- Becomes [3, 3]
- Same direction, just longer
- Stretch factor 3 is the eigenvalue
Eigenvectors are the directions a matrix keeps. In PCA, the biggest eigenvalue marks where your data spreads the most.
The big ideas
What you need to know
A v = λ v
Multiply the eigenvector v by the matrix A and you get the same v scaled by a number λ, the eigenvalue.
Eigenvalue = stretch amount
λ = 3 triples the length, λ = 0.5 halves it, a negative λ flips the direction.
PCA uses them
PCA finds eigenvectors of the data's covariance matrix. The top ones become new axes that keep most of the variation.
Let numpy do it
np.linalg.eig gives eigenvalues and eigenvectors. You need the idea more than hand calculation.
See it in code
Walk through the code
1import numpy as np2 3A = np.array([[2, 1],4 [1, 2]])5vals, vecs = np.linalg.eig(A)6print(vals) # [3. 1.] (order can vary)7 8v = vecs[:, 0] # eigenvector for 3, about [0.707, 0.707]9print(A @ v) # [2.121 2.121]10print(3 * v) # [2.121 2.121] same thing11 12u = np.array([1, 0])13print(A @ u) # [2 1] direction changed1/3eig returns all eigenvalues and a matrix whose columns are the eigenvectors.
numpy returns unit-length eigenvectors as columns. A @ v equals 3 * v, which is the whole definition in action.
Save yourself the pain
Common mistakes
Oops
Reading eigenvectors from the rows of the result.
Do this instead
numpy puts each eigenvector in a column: vecs[:, i] goes with vals[i].
Oops
Thinking eigenvectors have one correct length.
Do this instead
Any scaled copy is also an eigenvector. Libraries return length 1 by convention.
Your mission
Spot the stretch directions
Quick check
For a matrix A, A @ v gives exactly 2 * v. What does that tell you?
Go deeper
- 1Compute eigenvalues/eigenvectors for a small 2x2 matrix by hand.
- 2Learn how PCA uses eigenvectors of the covariance matrix to find directions of maximum variance.
- 3Visualize how eigenvectors define the axes a linear transformation stretches along.
More topics at this stop
 Linear Algebra Basics (Vectors, Matrices)
 Matrix Operations
 Calculus Basics (Derivatives, Gradients)
 Chain Rule
 Partial Derivatives
 Probability Fundamentals
 Probability Distributions
 Bayes' Theorem
 Descriptive Statistics
 Hypothesis Testing
 Correlation vs Causation
 Optimization Basics (Gradient Descent)

Stuck on this topic? Ask an Insider
Get 1:1 guidance from people who've walked this exact path — on the InsideEdge app.
